Our platform, NOVA, enables rapid development and validation of algorithmic trading strategies through the use of highly configurable and composable models and rigorous backtesting and simulation.
Doomsun's systematic trading platform used to develop, test, deploy, and manage strategies.
Reusable alpha and risk models, stateless and composing through defined interfaces. Portfolio and execution behavior is declarative configuration, stored as data and versioned over time.
An accumulate-only store. Every decision traces back to the data and model state that produced it, which is what makes a result reproducible a year later.
A structured surface for an agent to work against rather than a codebase to modify, so the platform absorbs advances in AI-assisted research as they arrive.
Strategy research through reproducible experiments, reusable models, and retained evidence.
Backtesting and simulation, with production execution behavior and traceable results for research assessment.
Characterizing what the current market structure is, how it is evolving, and what it implies for the near term.
Durable edge comes from the process that produces strategies, not from any one of them. Strategies emit probabilistic forecasts rather than buy/sell calls; those forecasts are scored for calibration, and capital follows the score. Individual strategies do not have to be regime-aware — only the scoring and allocation layer does.
Rotates back when the regime turns in its favor

Strategy research through controlled experiments.
Cyclotron turns a market hypothesis into a reproducible experiment. Compose and parameterize reusable alpha and risk models, fit and calibrate them on separate data, and then assess a frozen candidate against criteria declared in advance. Cyclotron and Stellarator work together to run rigorous backtests and evaluate the results.
A mechanism to test
Set the plan, fit models, and freeze parameters before testing.
Execute held-out splits. Return evidence.
Assess outcome paths
Approve deployment to NOVA Core.
Changed hypothesis? Start a linked candidate.
Cyclotron sets the protocol for combinatorial purged cross-validation (CPCV): multiple held-out splits, with purging and embargoes to reduce leakage between training and evaluation data. Stellarator executes the backtests; Cyclotron assesses results across the resulting outcome paths.
Attempts are recorded before work begins. Failures stay in the trial history, and changes to frozen inputs or parameters create a linked successor. The record explains what was tried, not just what worked.
Cyclotron is designed for people and AI agents to work through scoped MCP tools. Separate access to data preparation, strategy design, and evaluation helps preserve each experiment’s integrity.

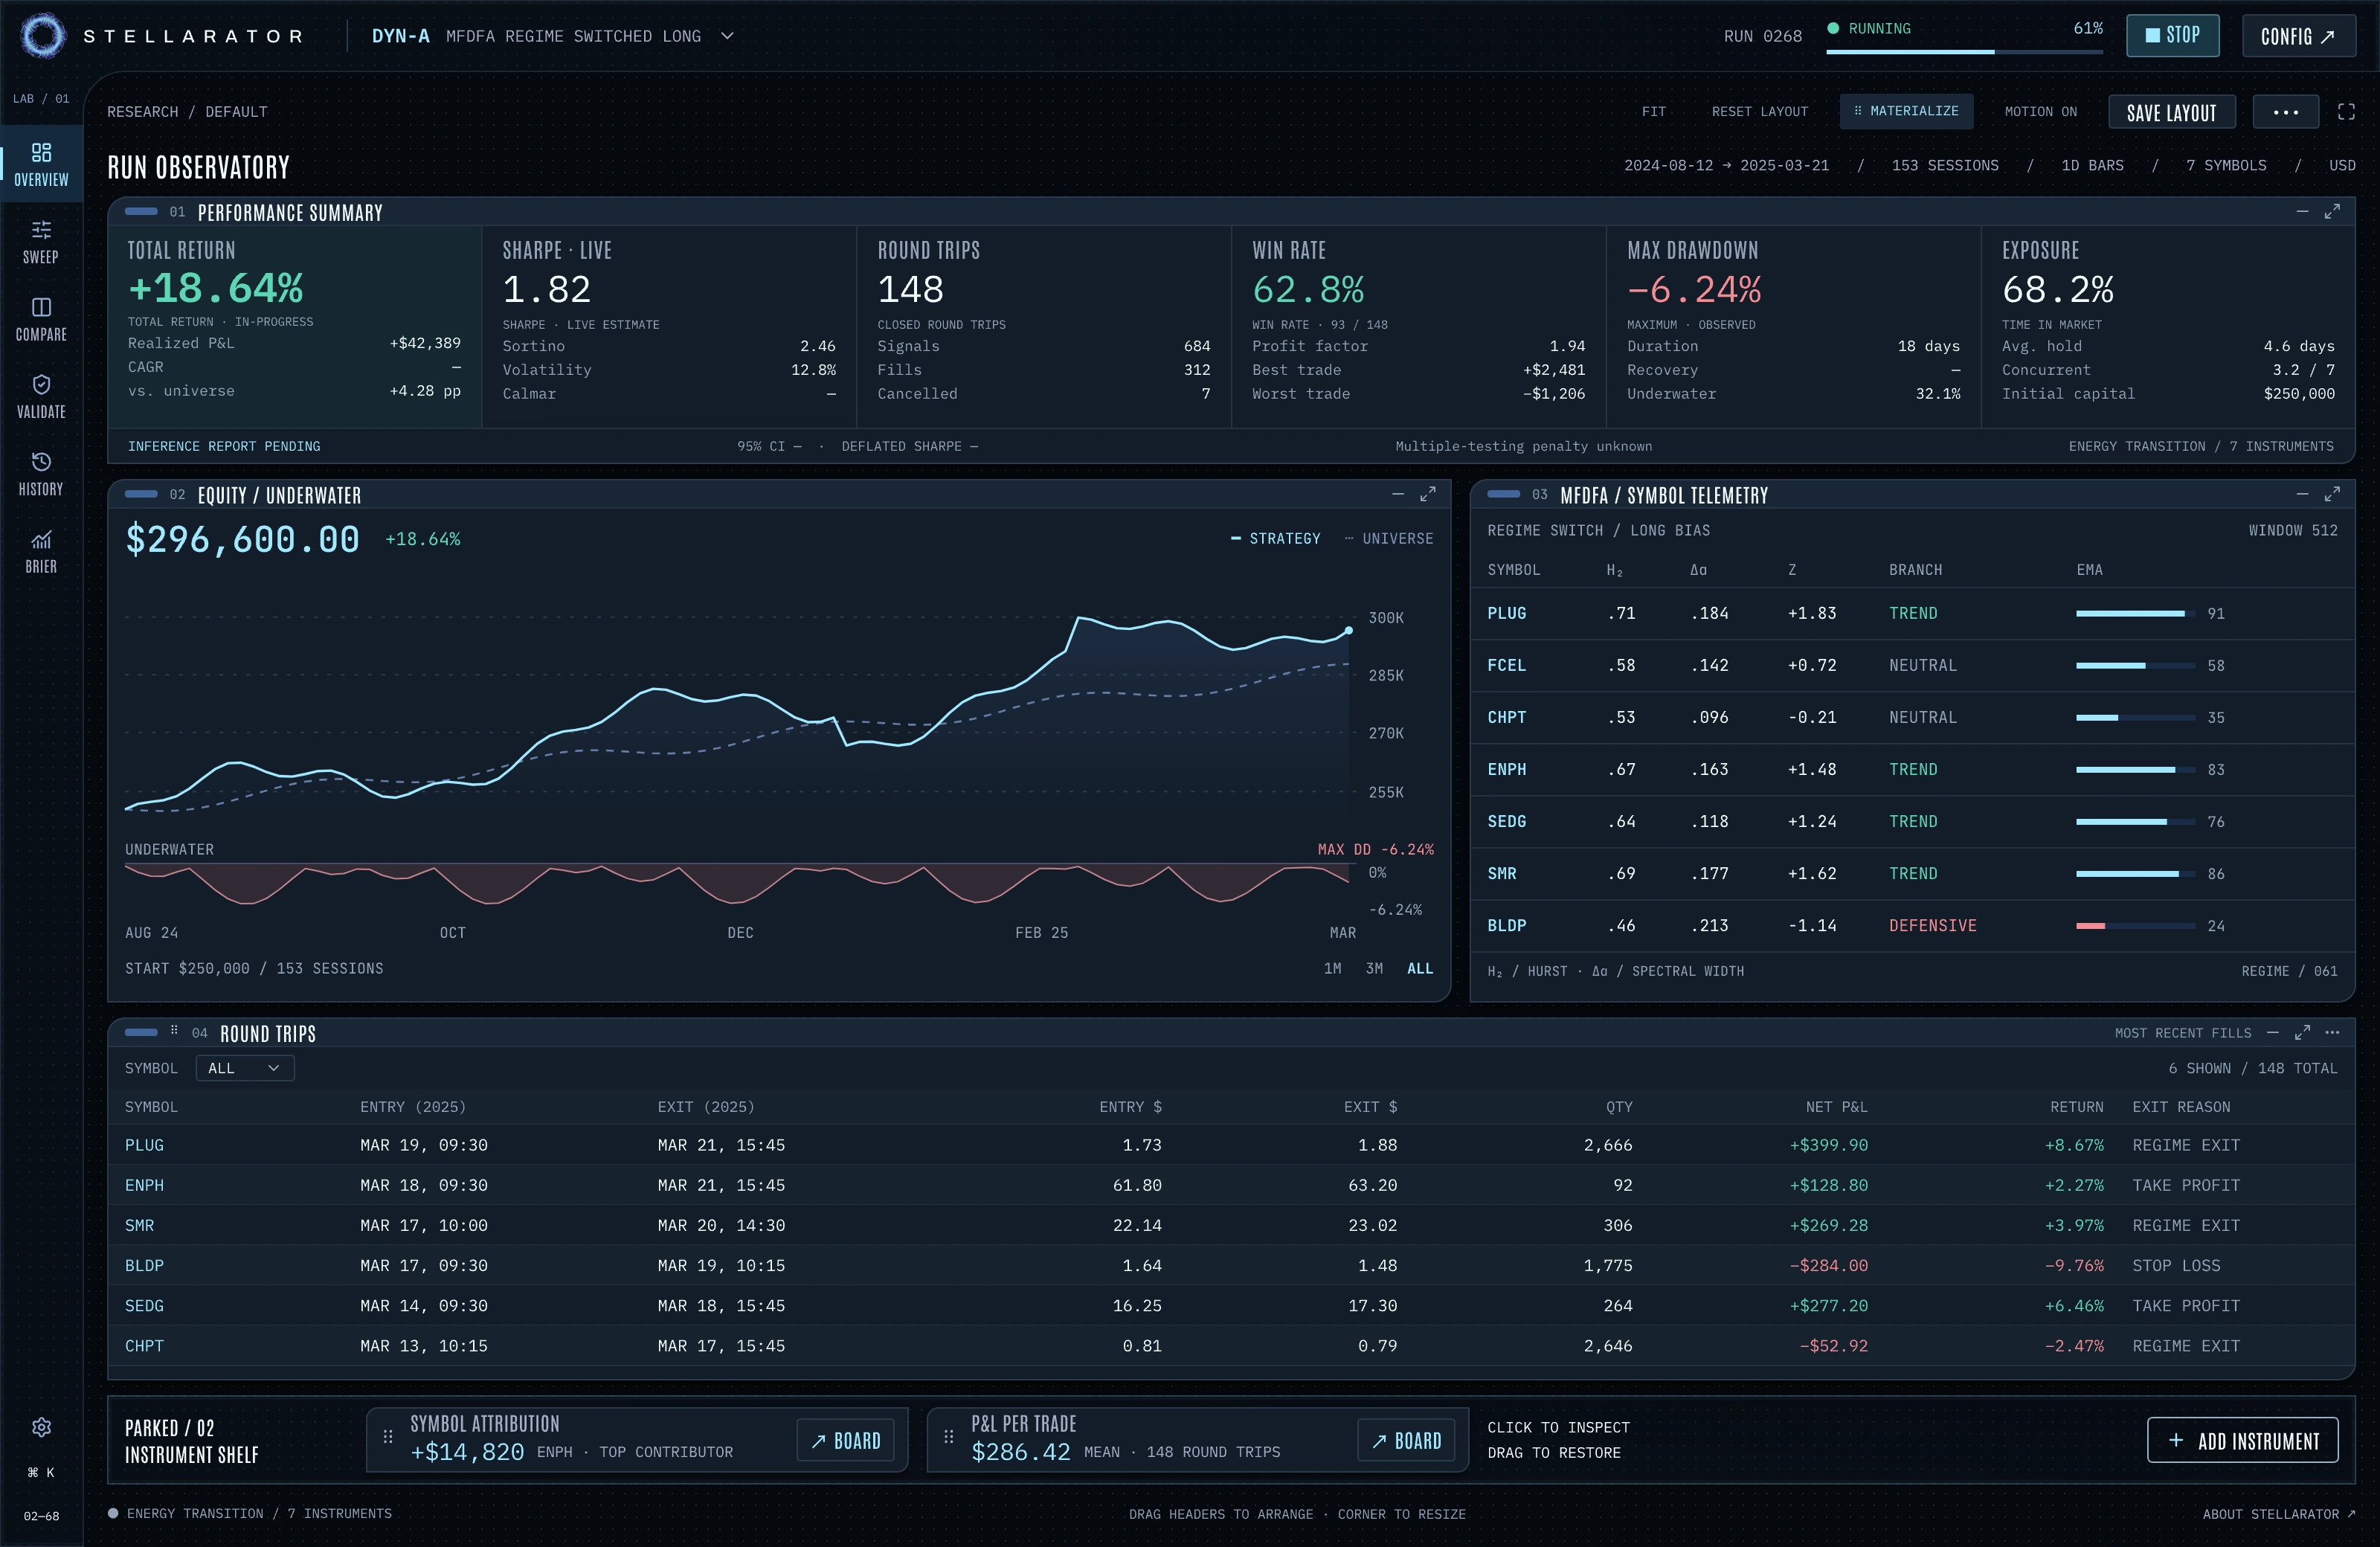
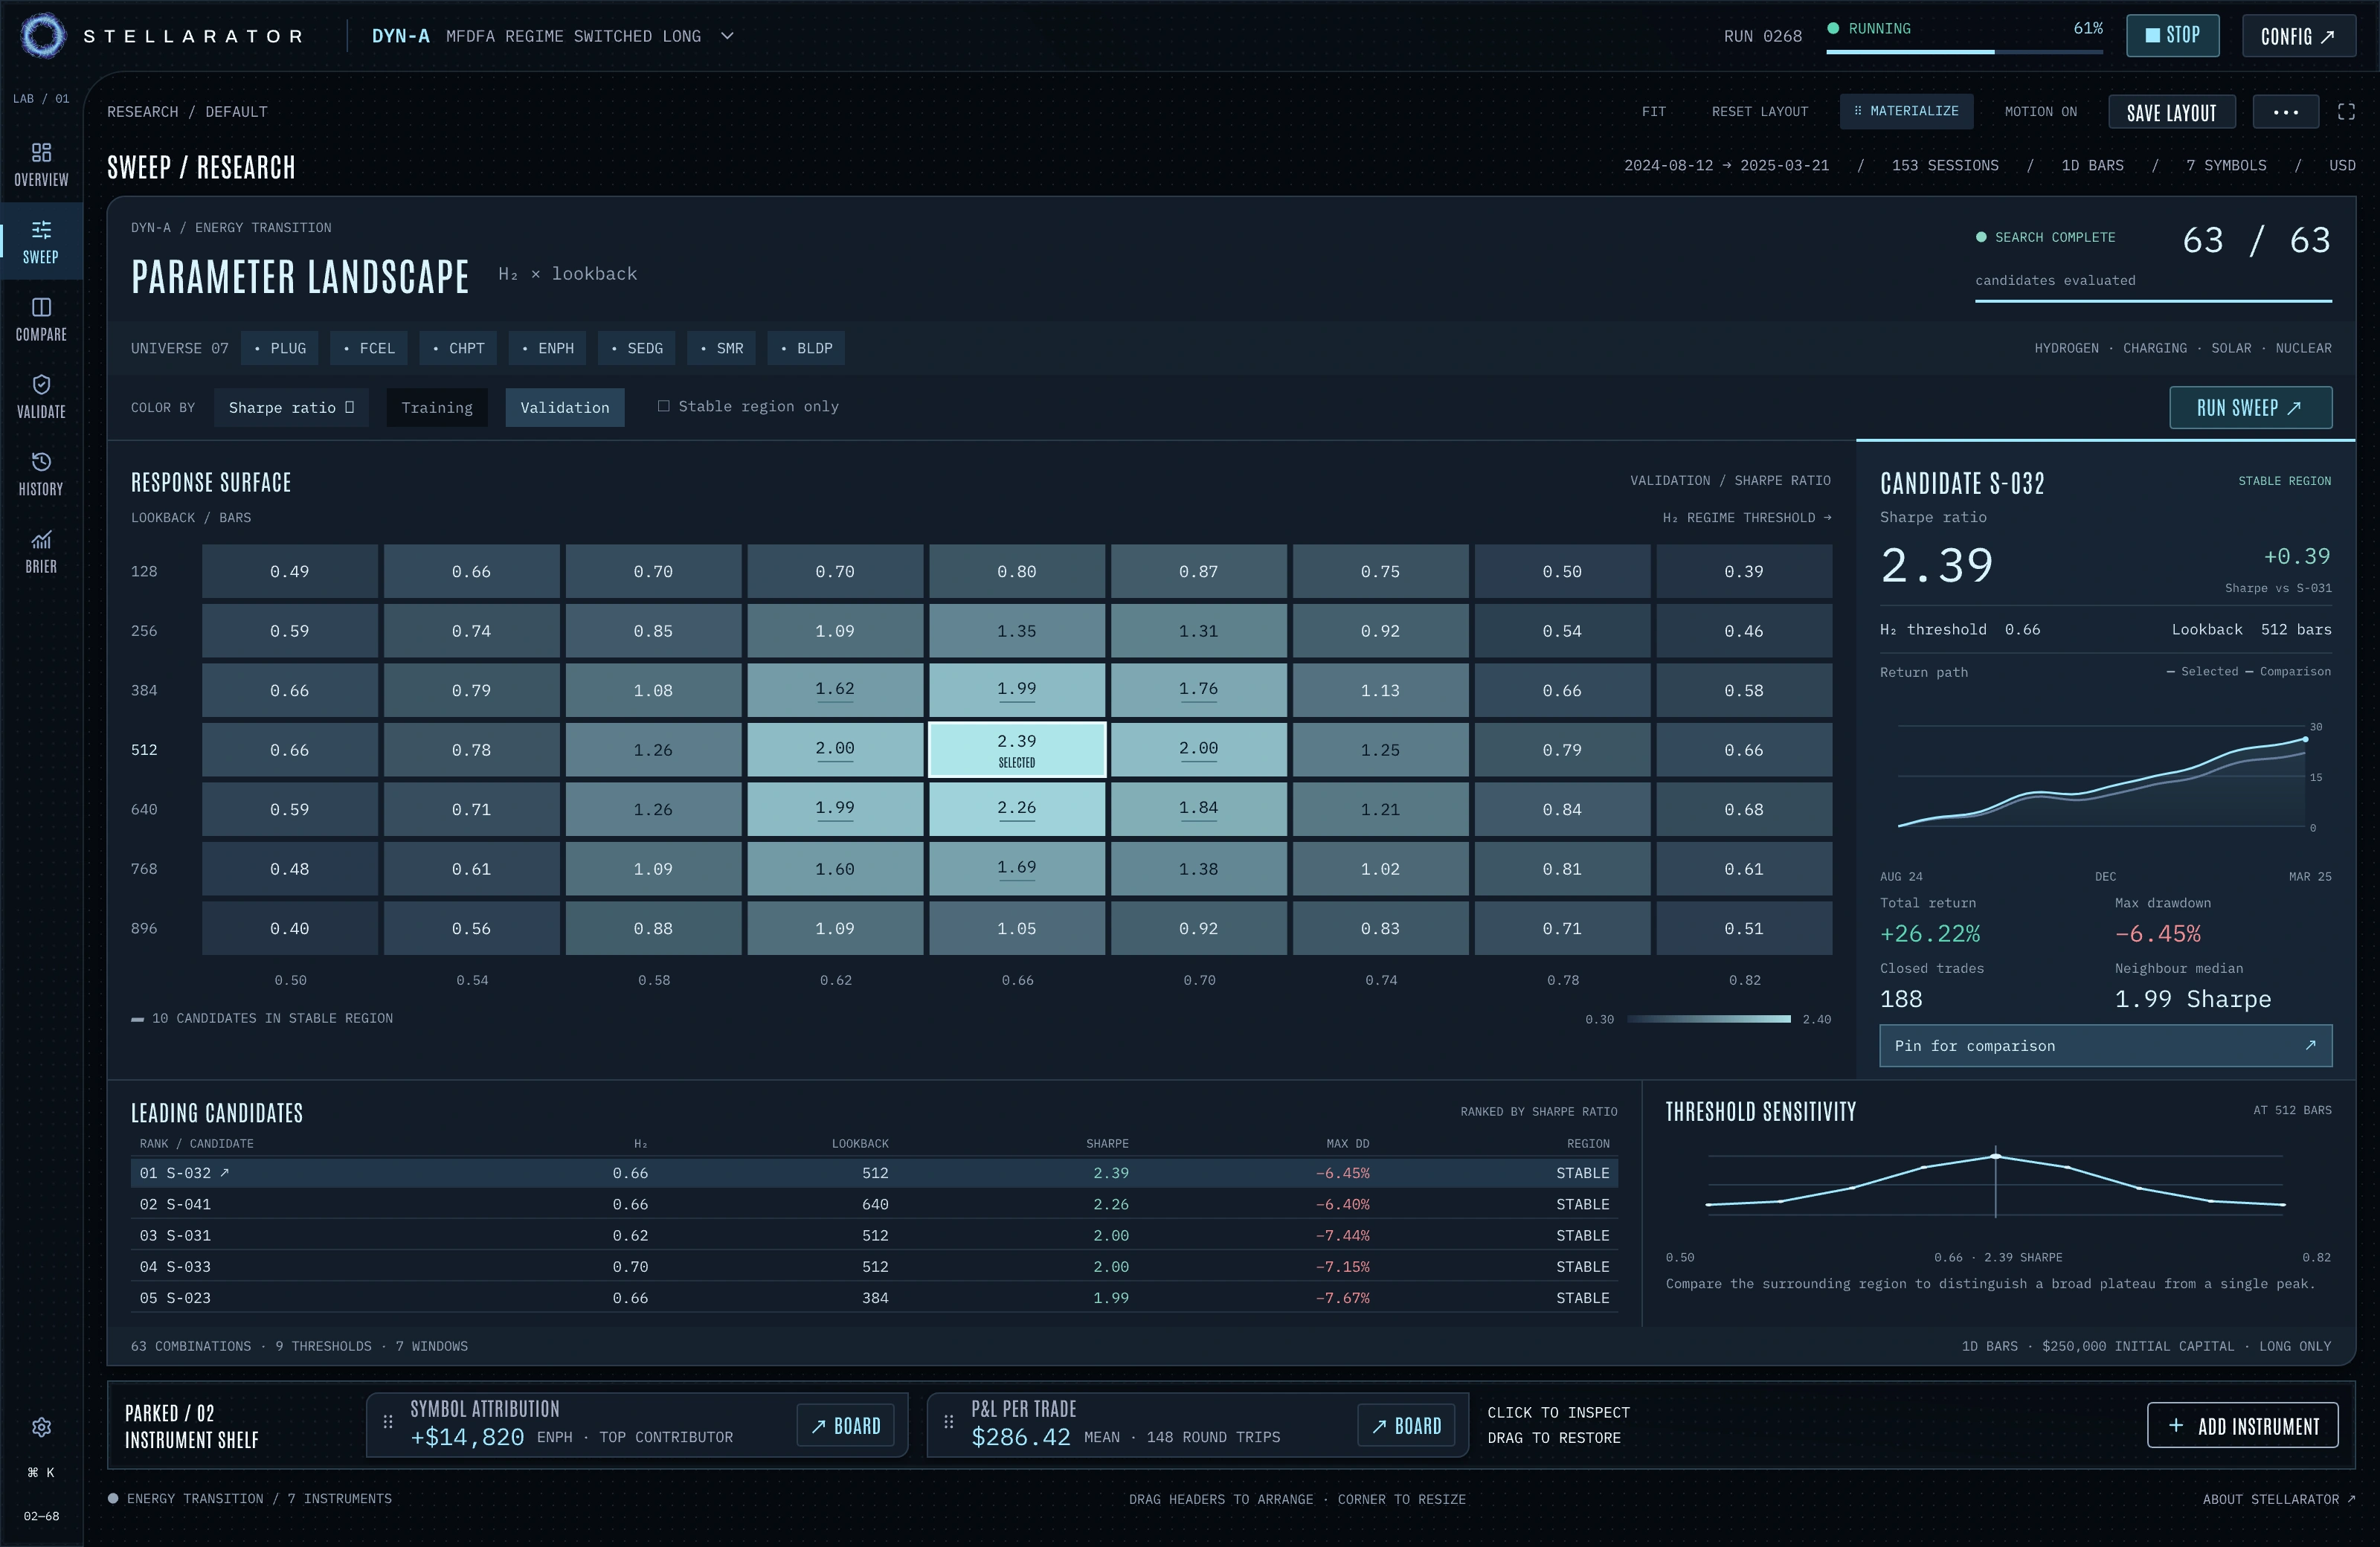
Execution realism, before a strategy touches capital. Stellarator runs backtests and simulations through the production execution path, returning the results Cyclotron uses for research assessment.
Strategies run in-situ, through the same path they take in production, with portfolio-level allocation and execution simulation covering slippage, partial fills, and market impact.
Cyclotron combines backtest results with trial history, verifies the evidence, and evaluates each candidate against the experiment’s criteria before deployment review.
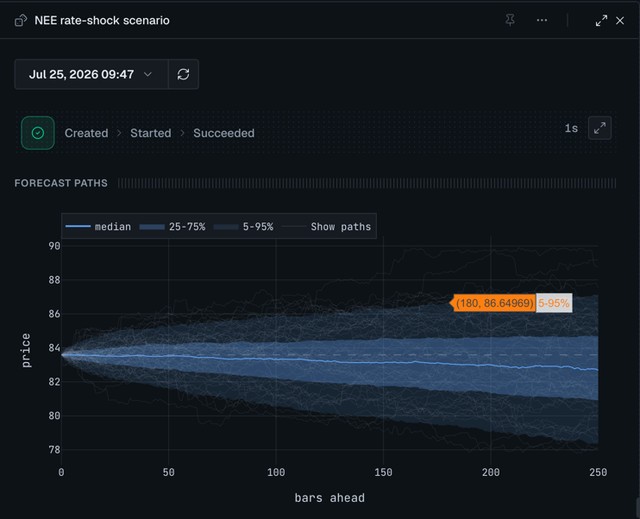
Forward simulation completes the picture: synthetic data calibrated to real structure, preserving the volatility clustering and fat tails that geometric Brownian motion cannot produce.

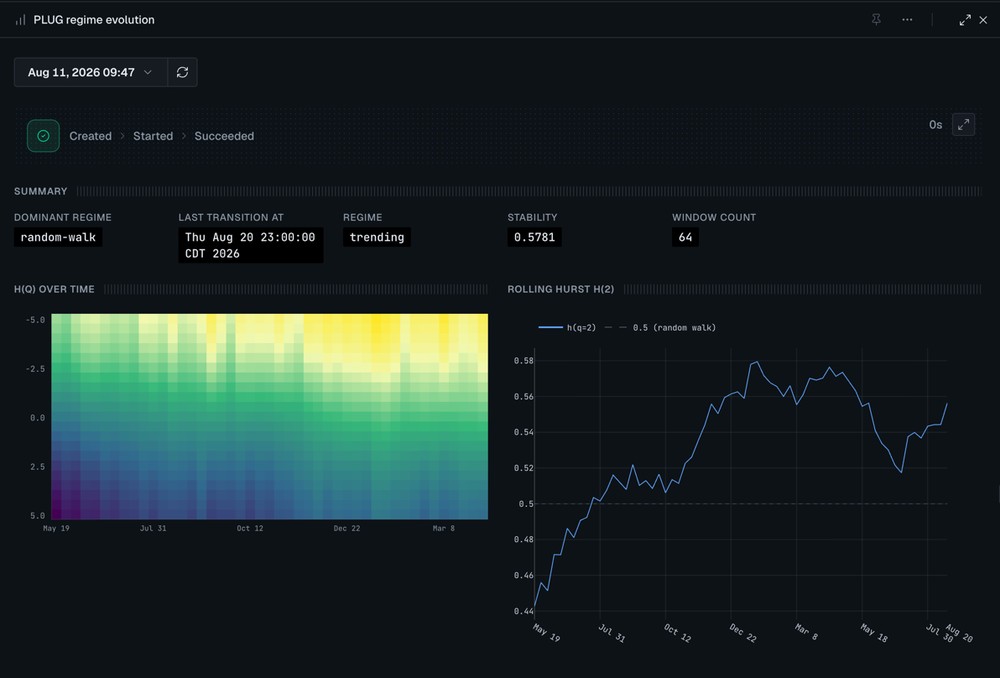
“Is this strategy still working?” is a lagging question — by the time returns answer it, the regime has already turned. Daylight asks what the market is currently capable of.
Multifractal analysis measures persistence, regime transitions, and directional asymmetry across timescales. Kinematics treats that structure as a trajectory rather than a snapshot, making the rate and direction of structural change the signal — comparable tools report a point value, this reports where it is heading.
An ML framework holding temporal context across price action, structural features, and cross-market signals. Structure feeds in as conditioning context, so one price pattern reads differently in a trending regime than in a chaotic one. Output is calibrated intervals, not point estimates.
Synthetic market data calibrated to a real market’s measured structure, preserving the volatility clustering and fat tails standard Monte Carlo cannot produce. Stellarator stress-tests strategies against those paths rather than the single one that happened.
Decades of experience in distributed systems, financial infrastructure, and algorithmic trading.

20+ years building distributed systems and fintech infrastructure

20+ years in consulting and fintech systems architecture